
UFIPA in Plain English: Florida’s New Rules for Smarter, Fairer Trusts
Florida’s adoption of the Uniform Fiduciary Income and Principal Act (UFIPA) is the most significant update to trust accounting in a generation. For trustees, beneficiaries, and anyoneinvolved in a trust, this isn’t just legal jargon; it’s a new set of rules designed to make trust administration more logical, fair, and adaptable to modern investing. Here’s what you need to know in plain English.
What is UFIPA? Cutting Through the Legal Jargon
UFIPA is a comprehensive state law that overhauls the rules for how trustees manage and distribute money from a trust. It replaces outdated, rigid guidelines with smarter, more flexible principles. The core purpose is to ensure balanced and equitable treatment between two groups: the income beneficiary (who receives regular payments from the trust’s earnings) and the remainder beneficiary (who receives what’s left of the trust principal later). This modernizes Florida trust accounting rules for the 21st century.
The End of the “One-Size-Fits-All” Approach
The old rules often forced trustees to invest in a way that generated immediate income (like bonds), which could hurt the trust’s long-term growth. UFIPA introduces a more nuanced duty.
The New Unitrust Standard: Fairness Through Percentages
A major UFIPA innovation is the endorsement of the “unitrust” concept. Instead of wrestling with separating complex investment returns into “income” and “principal,” a trustee can instead pay the income beneficiary a fixed percentage (e.g., 3-5%) of the trust’s total asset value each year. This automatically balances the needs of both beneficiaries for growth and income.
Expanded Power to Adjust
UFIPA gives trustees clearer authority to “adjust” between principal and income. If a trustee’s investment strategy, aimed at the best long-term results, creates too much or too little current income, they can reallocate funds to be fair to both types of beneficiaries without needing court approval.
Updated Rules for Specific Assets
The law provides clear, modern guidelines for handling complex assets that the old rules didn’t anticipate, such as:
- Pass-Through Entities: Rules for allocating income from LLCs, S-Corps, and other investments.
- Environmental Costs: How to handle expenses for cleaning up contaminated property held by the trust.
- Deferred Compensation: Clear rules for allocating payments from retirement plans and annuities.
Consider this illustrative scenario: A trustee is managing a trust with a growth stock portfolio for a surviving spouse (income beneficiary) and adult children (remainder beneficiaries). Under the old rules, the low dividend yield of the stocks provided little income for the spouse, forcing a difficult choice between the spouse’s needs and the children’s inheritance. Under UFIPA, the trustee can use the unitrust provision to pay the spouse a steady 4% of the portfolio’s value annually, ensuring her support while allowing the portfolio to grow for the children.
What This Means for Trustees and Beneficiaries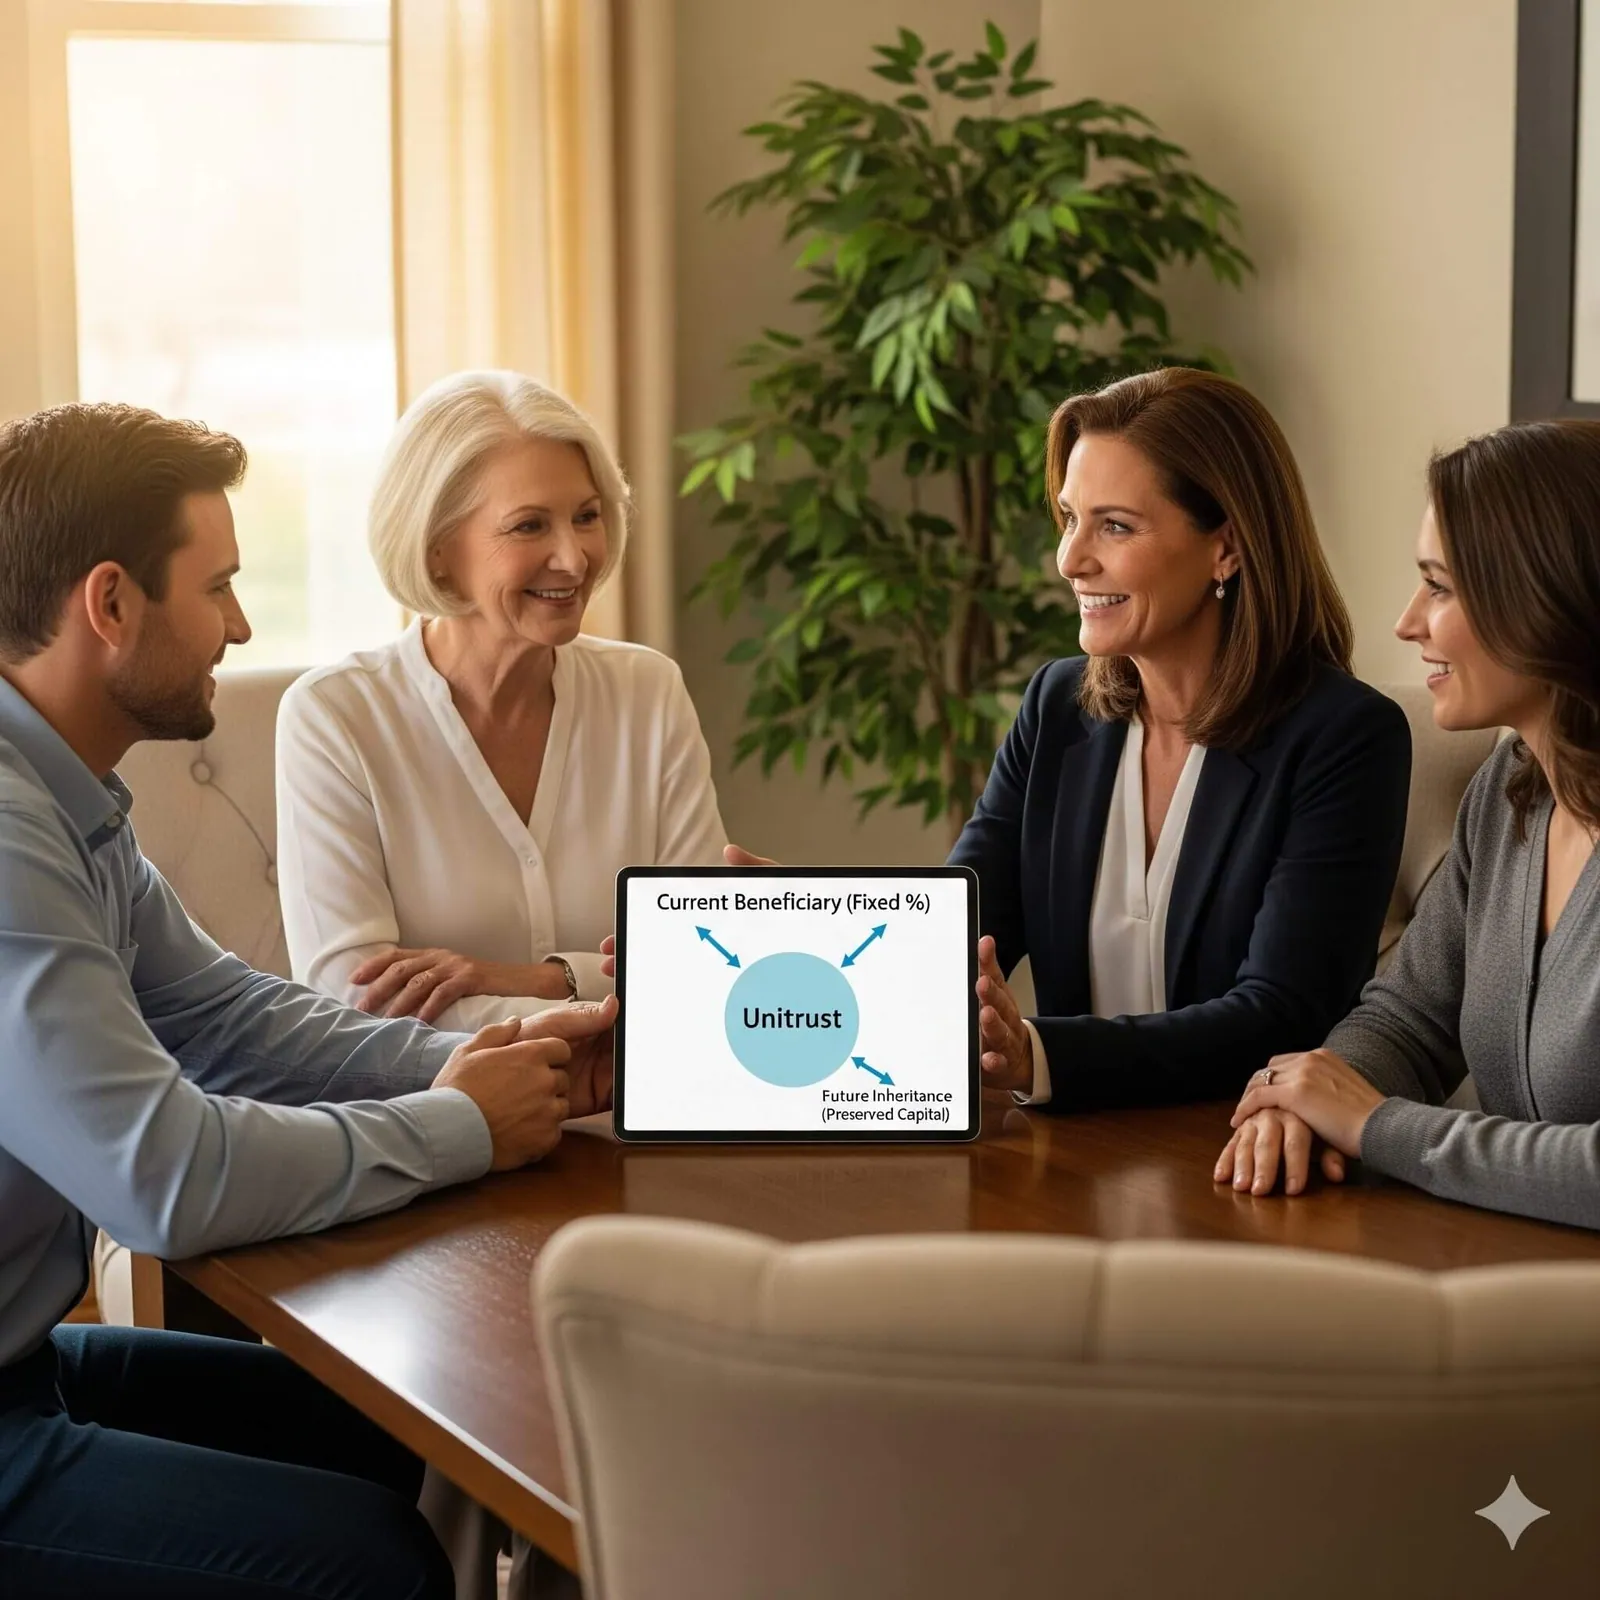
UFIPA changes the game for everyone involved in a trust.
For Trustees:
Your fiduciary duties have been updated. You now have more flexibility but also a greater responsibility to understand these new rules. Your investment strategy, accounting practices, and communication with beneficiaries must reflect UFIPA’s principles of impartiality and fairness. You must proactively review existing trusts to see if your strategies need updating.
For Beneficiaries:
You have a right to distributions that are fair under this new standard. If you are an income beneficiary, you should understand the unitrust concept. If you are a remainder beneficiary, you should understand how the trustee’s new adjustment powers might affect the long-term health of the trust. All beneficiaries should receive clear accountings that explain decisions made under UFIPA’s rules.
The Bottom Line: Modern Rules for Modern Wealth
Picture this: instead of being trapped by archaic accounting rules that pit family members against each other, your trustee has the tools to manage the trust fairly for everyone’s benefit. You feel the confidence of a system designed for today’s financial world, not the past’s. You see transparent and logical decisions that preserve family harmony and the trust’s purpose. This is the promise of UFIPA.
FAQ: UFIPA and Florida Trusts
What is UFIPA and how does it affect Florida trusts?
The Uniform Fiduciary Income and Principal Act (UFIPA) is a Florida law that modernizes the rules for how trustees allocate investment returns between income and principal. It affects all Florida trusts by providing new, flexible standards for trust investing, accounting, and distributions to ensure fairness between current and future beneficiaries.
How does UFIPA change trust accounting in Florida?
UFIPA changes trust accounting by moving away from rigid definitions of “income” and “principal.” It introduces concepts like the power to adjust and the unitrust election, allowing trustees to allocate funds based on what is fair and equitable for all beneficiaries rather than being forced to follow outdated mechanical rules.
Do trustees need to update trust practices under UFIPA?
Yes, absolutely. Trustees have a fiduciary duty to administer trusts under the current law. This means updating investment policies, account procedures, and beneficiary communication strategies to comply with UFIPA’s new standards for impartiality and modern portfolio management. Failure to do so could result in personal liability.