
New SALT Cap, New Trust Strategies: How High-Income Floridians Can Use Non-Grantor Trusts Under the Big Beautiful Bill
The One Big Beautiful Bill Act (“OBBBA”) did more than raise the standard deduction and extend lower brackets. It also changed one of the most controversial pieces of the 2017 tax reform: the cap on state and local tax (“SALT”) deductions.
For years, high-income taxpayers in places like New York, New Jersey, California, and Illinois have been squeezed by a $10,000 SALT cap. Starting in 2025, OBBBA temporarily opens that door much wider, and planners are already asking a natural question:
Can carefully designed, non-grantor trusts help families claim more of those SALT deductions, while still doing real estate and estate planning at the same time?
Even for Floridians, this matters. Many Brandon Legal Group clients:
- Own rental or commercial property in high-tax states,
- Have pass-through income from partnerships or S-corps based outside Florida, or
- Have children or grandchildren who live and work in high-tax states.
If that sounds like your family, the new SALT rules may mean your estate plan is also your tax plan.
What Changed: The New SALT Cap in Plain English
Under OBBBA, starting with the 2025 tax year, the SALT deduction cap is temporarily expanded. In simplified terms:
- The cap on state and local tax deductions increases from $10,000 to $40,000 per return for many households beginning in 2025, with modest annual increases through 2029.
- The higher cap is temporary; current law contemplates a reversion back toward the older $10,000 level around 2030.
- There are income-based phase-outs and thresholds. Many summaries note that the full $40,000 benefit is targeted toward households below certain adjusted gross income (AGI) levels, with limitations or a continuation of the $10,000 cap for those above specific AGI ranges.
The exact impact on you depends on:
- Your filing status and AGI,
- How much you pay in state income and property taxes, and
- Whether you itemize deductions or claim the standard deduction.
The important takeaway: for a limited window, there is more room on the federal return to deduct state and local taxes, especially for families with significant high-tax-state exposure.
Why This Matters to High-Income Floridians
 Florida itself has no state income tax. But many Floridians:
- Own rental or commercial real estate in high-tax states (for example, a New York City apartment building, a New Jersey shore rental, or a California duplex),
- Hold interests in pass-through entities (partnerships, LLCs, S-corps) operating in those states, or
- Have adult children working and paying high state income tax elsewhere.
That means you may be:
- Paying substantial state and local taxes each year, and
- Previously limited to deducting only $10,000 of that amount on your federal return.
With a higher SALT cap for a few years, the IRS is effectively offering you a

Non-Grantor Trusts 101: Who Pays the Tax?
To understand the planning conversation, you need one key distinction:
- Grantor trust: For income tax purposes, the IRS treats the individual grantor as the owner. Income, deductions, and credits all show up on the grantor’s personal return, even if the trust files an informational return.
- Non-grantor trust: The trust is its own taxpayer. It has its own income, deductions, and tax brackets. It files its own income tax return (Form 1041) and can claim its own SALT deductions, subject to the same kinds of caps and rules that apply to individuals.
In short, a properly structured non-grantor trust is a separate “tax bucket.” That is what has some planners talking about whether the new SALT cap might be captured, or even multiplied, for certain families by using multiple non-grantor trusts.
Important caution: this is a sophisticated strategy area. The IRS and some states have already signaled concern about artificial SALT cap “workarounds.” Any trust you create needs real, non-tax purposes (estate planning, asset protection, inheritance design) and must follow both federal and state law closely. In addition, real estate held inside a non-grantor trust is generally subject to the passive activity loss (PAL) rules at the trust level, which can be less favorable than the treatment an individual might receive if they qualify as a real estate professional. These PAL rules should be modeled carefully with your CPA before transferring income-producing property into a trust.
How Non-Grantor Trusts Can Help Under the New SALT Rules
1. Capturing SALT Deductions at the Trust Level
If a non-grantor trust:
- Owns high-tax-state real estate or pass-through interests, and
- Pays state and local tax on that income at the trust level,
then the trust itself may be able to:
- Claim SALT deductions up to its own cap, separate from your personal return, and
- Potentially reduce the overall family tax burden, assuming it is in a similar or lower tax bracket than you are.
Whether this works in practice depends on:
- Where the trust is taxed (trust residency rules vary by state),
- How much income stays in the trust vs. being distributed to beneficiaries, and
- How the SALT cap, AGI thresholds, and passive activity loss limits apply to that trust.
2. Helping Manage AGI Thresholds
Many provisions in the new law (including the SALT cap and other deductions or phase-outs) are tied to AGI thresholds. Concentrating all of the income from a multi-state portfolio on a single personal return can:
- Push your AGI above certain thresholds, and
- Limit your ability to benefit from the enhanced SALT cap or other deductions.
A non-grantor trust, when properly designed and funded, may:
- Hold a slice of those income-producing assets,
- Report some income and tax at the trust level instead of your personal return, and
- Allow both the trust and your individual return to use their respective SALT caps and thresholds, where permitted.
Again, this must be done with care. The IRS looks closely at arrangements that appear to exist solely to split income among entities without a genuine business or estate-planning purpose.
3. Classic Estate Planning Benefits at the Same Time
Even if the SALT benefits end up modest, non-grantor trusts can still deliver traditional planning advantages:
- Removing growth from your taxable estate: Once assets are in a properly structured irrevocable trust, future appreciation can occur outside your estate, helping manage future estate tax exposure.
- Asset protection: Trusts can provide protection against beneficiaries’ creditors, lawsuits, or divorces, depending on structure and state law.
- Structured inheritance: You can control how and when children or grandchildren receive funds (for example, for education, health, home purchases, or business ventures) instead of handing everything to them outright.
When done right, the SALT angle becomes one layer on top of a structure you may want anyway for family and legacy reasons.
The “Multiple Trusts” Conversation: Theory vs. Reality
Because each non-grantor trust is its own taxpayer with its own SALT cap, some commentators are talking about using multiple trusts to “multiply” that cap across a family.
In theory, a family could:
- Create separate non-grantor trusts for different children or branches of the family,
- Fund each with its own set of high-tax-state assets or pass-through interests, and
- Allow each trust to claim its own SALT deductions and apply its own AGI thresholds.
In practice, there are serious considerations:
- Substance over form: Each trust must have a real, independent purpose and set of beneficiaries. A collection of nearly identical “cookie-cutter” trusts created only to chase SALT deductions can attract IRS scrutiny.
- State law limits: Some states have enacted rules or taken positions specifically targeting “SALT cap workaround” trust structures.
- Passive Activity Loss (PAL) constraints: When income-producing real estate is moved into a non-grantor trust, the ability to use real estate losses can change. Trusts are generally subject to the passive activity loss rules at the trust level, which may be more restrictive than the treatment available to an individual who qualifies as a real estate professional. This can offset some of the anticipated tax benefit if not modeled carefully.
- Administrative cost: Each trust means its own legal setup, tax return, accounting, and investment management. For some families, the cost can outweigh the tax benefit.
- Short shelf life: The higher SALT cap is currently scheduled to last only a few years. Planning has to make sense even if the cap eventually drops back to $10,000.
Bottom line: the “multiple non-grantor trust” conversation is happening in the planning community, but it is not a simple do-it-yourself strategy. It requires careful modeling, legal analysis, and a clear narrative that this is first and foremost an estate and asset-protection structure, with tax as a secondary benefit.
Example: A Florida Couple with New York Rental Property
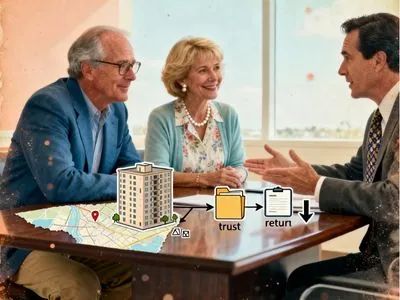 They are Florida residents for income tax purposes.
- They own a small apartment building in New York that generates both income and significant New York state and local taxes each year.
- They are already close to or above the AGI thresholds where federal deductions phase down.
An updated plan might look like:
- They create a carefully drafted non-grantor trust for the benefit of their children, with strong asset protection and long-term inheritance provisions.
- They transfer an interest in the New York rental property (or in the entity that owns it) into that trust, using some of their enhanced lifetime gift exemption as appropriate.
- The trust, not the couple, begins reporting a portion of the New York income and paying related state and local taxes.
Depending on trust residency rules, income levels, distributions, and the passive activity loss limitations that apply to the trust, this structure might:
- Allow the trust to claim SALT deductions up to its own cap,
- Shift some income off the couple’s personal return (helping manage AGI), and
- Move future growth in the property out of their taxable estate while building a protected inheritance for their children.
This is not a one-size-fits-all strategy. But it shows how estate planning and tax planning now intersect in a more powerful way under the new SALT rules.
When This Probably Is Not for You
Non-grantor trust SALT planning is unlikely to make sense if:
- You do not pay substantial state and local taxes outside Florida,
- Your total itemized deductions are well below the standard deduction,
- You prefer total simplicity over any potential tax savings, or
- You are uncomfortable giving up control or ownership in order to achieve estate-planning and asset-protection goals.
In those cases, a more straightforward Florida-focused estate plan may be the better choice, with SALT implications as a secondary consideration.
Next Step: When Your Estate Plan Is Also Your Tax Plan
If you:
- Own significant income-producing property or business interests in high-tax states,
- Have children or beneficiaries living and working in those states, or
- Are already paying more in state and local taxes than the old $10,000 cap ever allowed you to deduct,
then the new SALT rules under OBBBA may be a signal that it is time to look at your structure, not just your next tax return.
At Brandon Legal Group, we work with your CPA and financial team to:
- Map out where your income and property really live,
- Identify whether non-grantor trusts or other structures could reasonably improve your position, and
- Design trusts and entities that make sense for your family, asset protection, and legacy goals first, with tax benefits as an added layer.
If you have significant income or property outside Florida, the new SALT rules may mean your estate plan is also your tax plan. The right time to explore that connection is while the higher caps are in place, not after they expire.
FAQ: SALT Cap Planning and Non-Grantor Trusts
Is using non-grantor trusts to “multiply” the SALT cap clearly allowed?
The tax code does not explicitly bless a strategy of creating multiple non-grantor trusts solely to multiply the SALT cap, and the IRS has expressed concern about SALT “workaround” structures in the past. Each trust must have real economic substance, distinct beneficiaries, and valid non-tax purposes such as asset protection or long-term inheritance planning. Any strategy in this area should be modeled and vetted carefully with tax and legal advisors.
Do I lose all control if I use a non-grantor trust?
To be a true non-grantor trust for income tax purposes, certain powers and benefits must be given up or restricted. However, you can still retain significant influence by choosing a trusted trustee, defining clear distribution standards, and building in mechanisms for trustee removal or replacement. The exact level of control must be balanced against tax and asset-protection goals.
Does this only help if I live in a high-tax state?
No. Many Floridians who pay no Florida income tax still own property or business interests in high-tax states or have children and grandchildren living there. For those families, the expanded SALT cap and the use of non-grantor trusts can still be relevant, even though their primary residence is in Florida.
Will the SALT cap stay at $40,000 forever?
Current law increases the cap from $10,000 to $40,000 and then indexes it modestly through 2029, with a reversion toward the old cap in 2030 unless Congress acts again. That means the higher cap is a temporary opportunity, not a permanent feature, and planning should be evaluated in that time frame.
What should I do before considering a non-grantor trust strategy?
Start by gathering information: where your income originates, how much you pay in state and local taxes, your current estate plan, and your long-term goals for family and legacy. Then, meet with an estate planning attorney and your CPA together. The decision to use non-grantor trusts should grow out of a complete picture of your finances, not just a desire to chase a single deduction, and should take into account passive activity loss rules that may apply differently at the trust level than on your individual return.
This article is for general educational purposes only and is not legal, tax, or financial advice. The rules governing SALT deductions, trusts, passive activity losses, and income taxation are complex and may change. You should consult with your own qualified advisors before implementing any strategy described here.