
From Tax Bill to Legacy Plan: Using the New Exemption, Trump Accounts, and Trusts for Children & Grandchildren
The One Big Beautiful Bill Act (“OBBBA”) did more than make headlines. It reshaped the long-term planning landscape for families who want to turn today’s tax law into tomorrow’s legacy.
In broad strokes, OBBBA:
- Raises the federal estate and gift tax exemption to $15 million per person (with inflation adjustments going forward), and
- Creates new, tax-favored “Trump Accounts” that allow families to save for children under 18 with powerful tax benefits if the rules are followed.
For parents and grandparents, that combination is less about politics and more about opportunity. Used thoughtfully, it can become a complete legacy toolkit that:
- Protects your own retirement and lifestyle,
- Gives children and grandchildren a meaningful financial head start, and
- Wraps all of that inside a structure that can survive divorce, creditors, and family conflict.
The key is coordination. Instead of scattering money into random accounts at different banks, you want each dollar to have a job in an intentional, written plan.
 The New $15 Million Estate & Gift Exemption: More Room to Work With
Under OBBBA, the federal gift, estate, and generation-skipping transfer (GST) tax exemption is now $15 million per person, indexed to inflation going forward. For a married couple, that effectively means up to $30 million combined, assuming proper planning and elections are made.
In practical terms, that larger exemption gives families more room to:
- Transfer assets out of a taxable estate during life,
- Set up spousal lifetime access trusts (SLATs) so one spouse can still access funds,
- Fund irrevocable life insurance trusts (ILITs) to pay future estate tax or provide liquidity, and
- Support multi-generation planning with dynasty or GST-exempt trusts.
It also reduces the pressure to “wait and see” out of fear that the exemption will suddenly drop in half. While no tax law is ever truly permanent, the current structure gives families a window where proactive lifetime gifting and trust planning make a lot of sense.
Florida note: Florida does not have a separate state estate or inheritance tax. For Florida families, that makes the federal exemption the main tax threshold to watch.
Trump Accounts: A First-Layer Savings Tool for Children
OBBBA also introduced Trump Accounts, a new category of tax-favored savings accounts for children under 18. The details are still evolving with IRS guidance, but at a high level:
- Eligible children under 18 can have a Trump Account established in their name.
- For certain birth years (for example, children born in the mid-2020s under current rules), the federal government provides a one-time seed contribution, often cited around $1,000, as a jump-start.
- Family members (and, in some cases, employers or qualifying organizations) can contribute up to an annual limit (generally up to $5,000 per year, combined).
- Funds grow with favorable tax treatment, often tax-deferred or tax-free if used and distributed according to the rules.
- At age 18, the account typically converts to an adult retirement-style or investment account, with rules that may allow tax-favored use for education, job training, starting a business, or a first home.

Think of a Trump Account as a child’s own starter account:
- It belongs to them,
- It grows over time while they are still young, and
- It can be aimed at specific life-launch goals like school, career, or a first house.
For most families, a Trump Account will sit alongside other vehicles, such as:
- 529 plans for education-focused savings, and
- Custodial accounts (UGMA/UTMA) or other small accounts for shorter-term needs.
The key difference is that Trump Accounts are built for long-term, tax-advantaged growth in the child’s name, making them a powerful “first layer” of savings in a wider legacy plan.
Trusts: The “Adult Supervision” Around Your Family’s Wealth
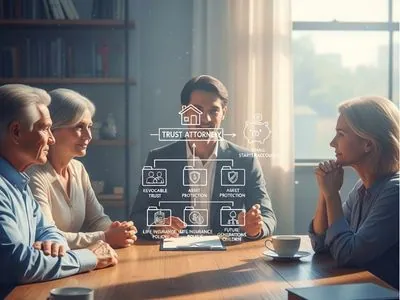 While Trump Accounts are great tools, they are not a complete estate plan by themselves. That’s where trusts come in.
Trusts allow you to:
- Decide who ultimately benefits (children, grandchildren, charities),
- Control when and how they receive funds,
- Protect assets from creditors, lawsuits, and future divorces, and
- Coordinate with your will, beneficiary designations, and business interests.
Common trust tools in a post-OBBBA world include:
- Revocable living trusts to avoid probate and provide a roadmap for incapacity and death.
- Spousal Lifetime Access Trusts (SLATs), which let you use part of your $15 million exemption while keeping indirect access to funds through your spouse.
- Dynasty or multi-generational trusts designed to hold assets for children, grandchildren, and beyond, often with strong asset protection and GST planning.
- Irrevocable life insurance trusts (ILITs) to keep large insurance policies outside your taxable estate and to provide liquidity for future taxes or buyouts.
When you zoom out, the structure looks like this:
- The new $15M exemption gives you headroom to move significant wealth into trusts without incurring federal transfer tax.
- Trump Accounts give children their own tax-favored savings vehicles for early-life goals.
- Trusts act as the long-term “adult supervision” around everything, tying it together into a coherent legacy plan.
Sample Legacy Structures: How Families Can Use the New Rules
1. Grandparents: Using a $30 Million Combined Exemption for a Multi-Generational Trust
Imagine Florida grandparents in their late 60s with a combined net worth of $40 million, much of it in investments and a closely held business. Under the new rules:
- Each grandparent has a $15 million federal exemption, for a combined $30 million.
- They decide to use $20 million of that exemption now to fund a multi-generational dynasty trust for children and grandchildren.
The trust can be designed so that:
- The children receive discretionary support for major life events (education, buying a home, starting a business).
- Grandchildren have access for similar purposes, but only under clearly defined rules that encourage responsibility.
- Trust assets are generally protected if a child later divorces, is sued, or has creditor problems.
Inside that trust, the family can even choose to:
- Match (or supplement) contributions to grandchildren’s Trump Accounts, and
- Fund 529 plans or other education vehicles as part of the overall design.
Result: the grandparents reduce their taxable estate, move growth into a protected structure, and create a financial “backbone” for future generations.
2. Parents: Trump Accounts + 529s for Education and First-Home Goals
Now imagine parents in their 40s with a growing business and two young children.
Their plan might look like:
- Open Trump Accounts for each child and make regular yearly contributions up to the allowed limit, letting those funds grow for future “launch” goals (education, first home, starting a business).
- Layer in 529 plans specifically focused on tuition and qualified education expenses.
- Use revocable trusts and beneficiary designations to ensure that, if something happens to them, a responsible trustee steps in to manage both Trump Accounts (where possible) and other assets for the children’s benefit.
Here, Trump Accounts are the child-facing tool, something concrete and long-term for each child, while the parents’ trust and estate documents provide the adult oversight.
3. Coordinating Everything: From Random Accounts to a Written Plan
Without coordination, it’s easy to end up with:
- A few accounts at a bank,
- A 529 plan somewhere else,
- A life insurance policy with an outdated beneficiary, and
- No clear instructions for who manages what if something happens.
A coordinated plan, in contrast, will:
- Make sure beneficiary designations on Trump Accounts, IRAs, life insurance, and 529s match your overall estate plan.
- Use trusts to centralize decision-making in the hands of people you trust.
- Spell out how and when children step into responsibility as they age.
Instead of scattered decisions, your legacy becomes a single, intentional design.
Common Pitfalls to Avoid
Even with these new tools, there are traps:
- Assuming “permanent” means forever: Congress can change the rules. A good plan uses today’s law but is flexible enough to adjust.
- Opening accounts without a bigger plan: A Trump Account is helpful, but by itself it is not an estate plan.
- Ignoring control and protection: Leaving large assets outright to children (or naming a minor as a direct beneficiary) can create problems in court, in divorce, or with creditors.
- Forgetting income tax and state law: Federal estate tax planning has to be coordinated with income tax planning and the rules of your home state.
Is This Only for the Ultra-Wealthy?
Not necessarily. If you:
- Own a business that might be sold in the next 5–10 years,
- Expect your net worth to cross a few million dollars, or
- Simply want to be intentional about what your children and grandchildren receive, and when,
then it is worth at least having a conversation about how the new exemption, Trump Accounts, and trusts might fit your situation.
Next Step: Turn Today’s Law into a Legacy Plan
At Brandon Legal Group, we help families connect the dots between:
- What the tax law allows them to do today, and
- What they want their family’s life to look like tomorrow.
If you are thinking about gifting, helping children with college or a first home, or planning for a business sale in the next decade, this is the moment to turn the new tax rules into a written legacy plan.
We can help you evaluate:
- How much of your $15 million exemption to use now versus later,
- Where Trump Accounts and 529s make sense for children and grandchildren, and
- What kind of trust structure offers the right balance of access, control, and protection.
The tax bill is already law. The legacy plan is what you build on top of it.
FAQ: New Exemption, Trump Accounts, and Trusts
Is the $15 million estate and gift tax exemption really permanent?
OBBBA makes the higher exemption levels permanent under current law, with inflation adjustments going forward. However, no Congress can bind a future Congress. The law can change again. That’s why many families choose to make strategic use of the exemption while it is available, but build flexibility into their overall plan.
How much can we put into Trump Accounts for our children?
Under current rules, Trump Accounts are designed for children under 18, with contributions up to an annual cap (generally up to $5,000 per year in combined contributions from family and other eligible sources, subject to future inflation adjustments and IRS guidance). Some children in defined birth years also receive a one-time federal seed contribution when the account is opened. The exact limits and details can vary as regulations develop, so it’s important to confirm the current numbers before contributing.
Do Trump Accounts replace 529 plans?
No. Trump Accounts and 529 plans serve different roles. Trump Accounts are broader child-focused savings vehicles that may support education, job training, starting a business, or buying a first home, depending on future rules and distributions. 529 plans are more tightly focused on education expenses. Many families will use both, targeting each tool at a different goal within the same overall plan.
How do trusts work with the new $15 million exemption?
The larger exemption gives you more room to move assets into trusts during life without triggering federal gift tax. Once in trust, those assets and their future growth can be kept outside your taxable estate, while providing structured benefits to children and grandchildren. Common strategies include funding dynasty trusts, SLATs, and ILITs using some or all of your available exemption.
What if we’re not sure our children are ready to handle significant wealth?
That is exactly what trusts are built for. You can appoint a trustee or co-trustees who manage assets and make distributions under standards you define (for example, health, education, maintenance, and support). You can also phase in control over time, allowing children to become co-trustees or sole trustees at specific ages. The new tax rules give you more room to fund those trusts; the trust terms give you the ability to apply “adult supervision” over how and when wealth is used.
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. The rules around OBBBA, Trump Accounts, and trusts are complex and may change. You should consult with your own legal, tax, and financial advisors about your specific situation before taking any action.