
The New $15 Million Estate Tax Exemption: What It Means for Florida Families in 2026 and Beyond
For educational purposes only. Not legal advice. Talk to a qualified attorney or tax professional about your specific situation.
If you live in Florida, it has always been easy to say, “There’s no estate tax here, so I don’t need to worry about it.” For a long time, that was mostly true. But with the value of homes, retirement accounts, and small businesses climbing, more Florida families were creeping toward the federal estate tax line.
Then, in 2025, everything changed again. President Trump signed the One Big Beautiful Bill Act (OBBBA), which permanently sets the federal estate and gift tax exemption at $15 million per person ($30 million per married couple) starting in 2026 – instead of letting it fall by about half when the old law was set to expire.
This is good news if you’re building wealth. It’s also a giant red flag if your will or trust was written for a completely different tax regime. At Brandon Legal Group, our job is not to pat you on the head – it’s to give you straight answers and a clear plan so you can protect your family and your legacy.
1. What Just Changed? A Simple Explanation of the New $15 Million Exemption
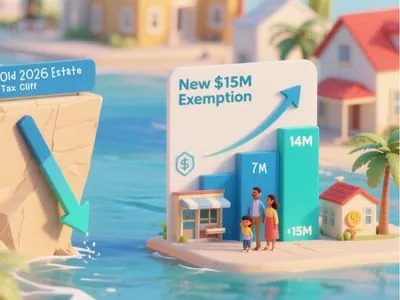 Before OBBBA, the 2017 tax law had temporarily doubled the estate, gift, and generation-skipping transfer (GST) tax exemptions. That “bonus” exemption was scheduled to expire at the end of 2025. Starting in 2026, the federal exemption would have dropped from roughly $14 million per person in 2025 to about $7.1 million, adjusted for inflation.
OBBBA stopped that cliff from happening and did more than that:
- It increases the federal estate, gift, and GST exemption to $15 million per person (about $30 million per married couple with proper planning) in 2026.
- It ties that $15 million number to future inflation, so it can continue to grow over time.
- It keeps the 40% estate tax rate on amounts above the exemption.
In plain English: for Florida families with significant property, businesses, or investment portfolios, the federal estate tax just got pushed farther out of reach – but not out of mind. The window to do smart planning just got wider.
2. “We’re Not That Rich” – Why This Still Affects Normal Florida Families
It’s easy to hear “$15 million” and tune out. But when we sit down and actually do the math with families in Brandon, Tampa Bay, and across Florida, the numbers add up faster than you think:
- Primary home + vacation home or rental property
- 401(k)s, IRAs, brokerage accounts
- A closely held business or professional practice
- Life insurance (often a seven-figure policy)
- Future inheritances or business sale proceeds you haven’t received yet
You don’t have to be “ultra-wealthy” to hit seven or eight figures on paper. And even if your net worth today is below $15 million, the real question is where you’ll be in 10–20 years:
- What happens if your business sells for eight figures?
- What if your real estate doubles again?
- What if you inherit from your parents and then pass everything down to your children?
Estate planning is about trajectory – not just today’s balance sheet. This new law gives you room to grow, but it also gives you an opportunity to lock in protections for your family while the rules are favorable.
3. The Old 2026 “Estate Tax Cliff” vs. the New Permanent Exemption
Under the pre-OBBBA rules, 2026 was going to be ugly from a planning standpoint. The federal exemption would have dropped by about half, overnight. Families who were “safe” in 2025 could suddenly be looking at an estate tax problem in 2026 with no warning other than a footnote in an old law.
OBBBA changed that:
- Instead of dropping to around $7.1 million, the exemption will rise to $15 million per person in 2026.
- Instead of a “temporary” bonus, the higher exemption is now written into law as the new baseline, with future inflation adjustments.
That doesn’t mean Congress can never change it again. It does mean we’re no longer planning around a built-in cliff. We’re planning around a higher, clearer line – and that’s a gift if you’re willing to use it.
4. Why Now Is the Time to Dust Off Your Estate Plan
Here’s the part where we’re blunt: if your will or trust is more than about 7–8 years old, or if it was drafted assuming much lower exemptions, it was built for a different tax world than the one we’re in now.
That doesn’t automatically make your plan “bad.” It does mean you should stop assuming it still does what you think it does.
 4.1 Outdated Formula Clauses (“Credit Shelter” / “Bypass” Language)
Many older wills and trusts use formula clauses that sound harmless but can create big problems with today’s numbers. Common language might say something like:
“The amount equal to the available estate tax exemption goes into the bypass (credit shelter) trust; the rest goes to my spouse.”
When the exemption was $600,000 or $1 million, that formula worked fine. When the exemption is $15 million, the formula can:
- Push all or almost all of the estate into a bypass trust, leaving the surviving spouse with little or nothing outright.
- Lock assets into a trust structure that made sense for tax reasons 20 years ago but may be overly complex or restrictive today.
We see this over and over: good documents written for the 1990s or 2000s quietly become bad fits in 2026.
4.2 Old A/B Trust Structures
For married couples, the classic “A/B trust” structure (splitting the estate into a marital trust and a bypass trust at the first death) was designed to squeeze every last dollar out of a low exemption and protect growth from estate tax at the second death.
In today’s environment, that same A/B structure might:
- Provide no tax benefit at all because your combined estate is under the new $30 million couple’s exemption, and
- Create unnecessary administrative work and restrictions for the surviving spouse.
On the other hand, if you’re in the range where $15–30 million is realistic, you may still want a version of this structure for tax and asset-protection reasons – but it needs to be tuned to the new exemption numbers and your current goals, not the fears of 1998.
4.3 Lifetime Gifts, SLATs, and Dynasty Trusts While the Window Is Open
The higher exemption doesn’t just help at death. It also increases what you can give away during life without gift tax:
- You can use part or all of your $15 million exemption to make lifetime gifts to children, grandchildren, or trusts.
- Those gifts, and all future growth on them, can be kept outside of your taxable estate.
Powerful tools in this environment include:
- SLATs (Spousal Lifetime Access Trusts): One spouse makes a gift into an irrevocable trust for the benefit of the other spouse and children. You remove assets from your estate but keep indirect access through your spouse.
- Dynasty Trusts / Multi-Generational Trusts: Properly drafted, these can hold wealth for children, grandchildren, and further generations, with protection from estate tax at each level, as well as from creditors and divorces.
- Gifting of business interests or real estate: Moving growth assets now, while valuations are still reasonable, can “freeze” what’s exposed to estate tax later.
The bottom line is simple: a higher exemption isn’t a reason to ignore planning; it’s a reason to be more aggressive and intentional with it.
5. The Florida Twist: No State Estate Tax, Still Big Decisions
Florida does not have its own estate or inheritance tax. That’s one of the reasons people move here. But the federal estate tax applies no matter what state you live in. The new $15 million exemption just pushes that line higher.
Florida families also have tools other states don’t:
- Florida homestead protections for the family home.
- Strong creditor protection for certain retirement accounts and life insurance.
- No state income tax on trust or estate income earned here.
Smart planning coordinates all of these Florida advantages with the new federal exemption. Done right, you can:
- Protect your home and retirement assets from unnecessary risk,
- Use trusts to protect children from divorces, lawsuits, and bad decisions, and
- Keep your family comfortably under the estate tax radar even as wealth grows over time.
6. Who Should Be Reviewing Their Plan Right Now?
You don’t need to be a billionaire for this law to matter. If any of the following sound like you, it’s time to stop guessing and have your plan actually reviewed:
- Your will or trust is more than 8–10 years old.
- Your plan uses A/B, bypass, or credit shelter trusts drafted before 2018.
- Your net worth (including life insurance and business interests) is approaching or above $5–7 million.
- You own a business you may sell in the next 5–10 years.
- You own significant real estate, especially multiple properties or investment rentals.
- You expect to receive a sizable inheritance yourself and then pass it on.
Even if you’re not close to $15 million today, planning around the new exemption gives you control and flexibility. Waiting until you “feel rich enough” is how families end up with rushed decisions and avoidable tax surprises.
7. Our Straight-Talk CTA: Bring In Your Old Documents
At Brandon Legal Group, our style is simple: no sugar-coating, no scare tactics, no vague promises. We sit down with you, look at your actual documents and your actual numbers, and tell you whether your plan fits the new law or not. :contentReference[oaicite:4]{index=4}
Call to action: “Bring in your old will or trust – let’s make sure it wasn’t written for a tax regime that no longer exists.”
If it still works, we’ll tell you. If it doesn’t, we’ll show you exactly what needs to change, and why, in plain English.
FAQ: New $15 Million Estate Tax Exemption & Florida Families
1. When does the new $15 million exemption actually start?
The increased exemption under the One Big Beautiful Bill Act is scheduled to take effect on January 1, 2026. For 2025, the exemption remains at the pre-OBBBA level (about $14 million per person). Starting in 2026, it becomes $15 million per person, indexed for inflation going forward.
2. Does Florida have its own estate or inheritance tax?
No. Florida does not have a separate state estate or inheritance tax. Only the federal estate tax applies. The new $15 million exemption is a federal rule that applies to Florida residents just like residents in every other state.
3. If our estate is under $5 million, do we really need to update our plan?
Probably, yes. The main reason is not just taxes – it’s structure. Many older documents were drafted with formulas, A/B trusts, or assumptions that no longer match your family or the current law. Updating your plan can simplify things for your spouse and children, clarify who is in charge, and line up your documents with your real-world goals, regardless of the exact tax threshold.
4. Could Congress change the exemption again in the future?
Yes. This law is “permanent” in the sense that it does not have a built-in sunset date, but no Congress can bind the next one. Future political shifts can raise or lower the exemption again. That’s why we plan around the law we actually have today, while building in flexibility in case the rules change later.
5. What is a SLAT, and why are people talking about them now?
A Spousal Lifetime Access Trust (SLAT) is an irrevocable trust one spouse creates for the benefit of the other spouse (and often children), using part of the creator’s lifetime gift/estate exemption. The assets and their future growth are removed from the taxable estate, but the couple can still benefit indirectly because the beneficiary spouse can receive distributions. With a $15 million exemption, SLATs are a powerful way to “use” the exemption while keeping practical access to the funds.
6. What is a dynasty trust?
A dynasty trust is a long-term trust designed to last for multiple generations. If it’s properly structured and funded using your lifetime exemption and GST exemption, assets in the trust can grow and be used for children and grandchildren without being hit with estate tax at each generation – and with strong protection from creditors and divorces. The higher $15 million exemption makes this kind of multi-generational planning much more accessible.
Ready to stop guessing? Schedule a review, bring your documents, and let’s make sure your estate plan is built for the $15 million era – not the tax world of 20 years ago.